A Lower Price or Help With Closing Costs—Which Is Better When Buying in Maryville, TN?
A Lower Price or Help With Closing Costs—Which Is Better When Buying in Maryville?
By Jessica Garcia, REALTOR® — EPIQUE Realty
You find a home in Maryville that checks your boxes. You’re ready to make an offer, and there may be an opportunity to negotiate.
Now comes a question buyers don’t always think to ask: Would a lower purchase price help you more, or would help with closing costs make the bigger difference?
Both can be valuable. The right choice depends on your available cash, your monthly budget, and the terms of your loan.
What a lower purchase price does for you
Negotiating a lower price reduces what you pay for the home. Depending on how your financing is structured, it can also reduce your loan amount, your required down payment, and your monthly principal-and-interest payment.
But the monthly difference may be smaller than you expect.
For example, a $10,000 price reduction doesn’t mean you’ll need $10,000 less cash at closing when you’re financing most of the purchase. Your lender can calculate exactly how that reduction changes your loan.
A lower price may be especially useful when your priority is reducing your purchase cost and ongoing payment.
What seller-paid closing costs do for you
Buying a home takes more cash than the down payment alone. You also have closing costs and other upfront expenses.
As part of your offer, you can ask the seller to contribute toward eligible costs. That contribution is commonly called a seller credit.
An agreed seller credit can reduce the amount you need to bring to the closing table. Your Loan Estimate includes seller credits in its calculation of estimated cash to close.
That could help preserve savings for moving expenses, repairs, or the surprises that come with owning a home.
Closing-cost help may be especially useful when your monthly payment works, but the upfront cash requirement feels tight.
Your lender must confirm how much seller assistance your loan allows and which expenses it can cover. A seller credit generally cannot cover your required down payment, and unused credit typically isn’t cash you can take home.
Compare two offers on the same home
Imagine a Maryville home listed at $350,000. You could ask for a lower purchase price, or you could offer the asking price and request help with eligible closing costs.
Here’s a hypothetical example—not a current listing or mortgage quote:
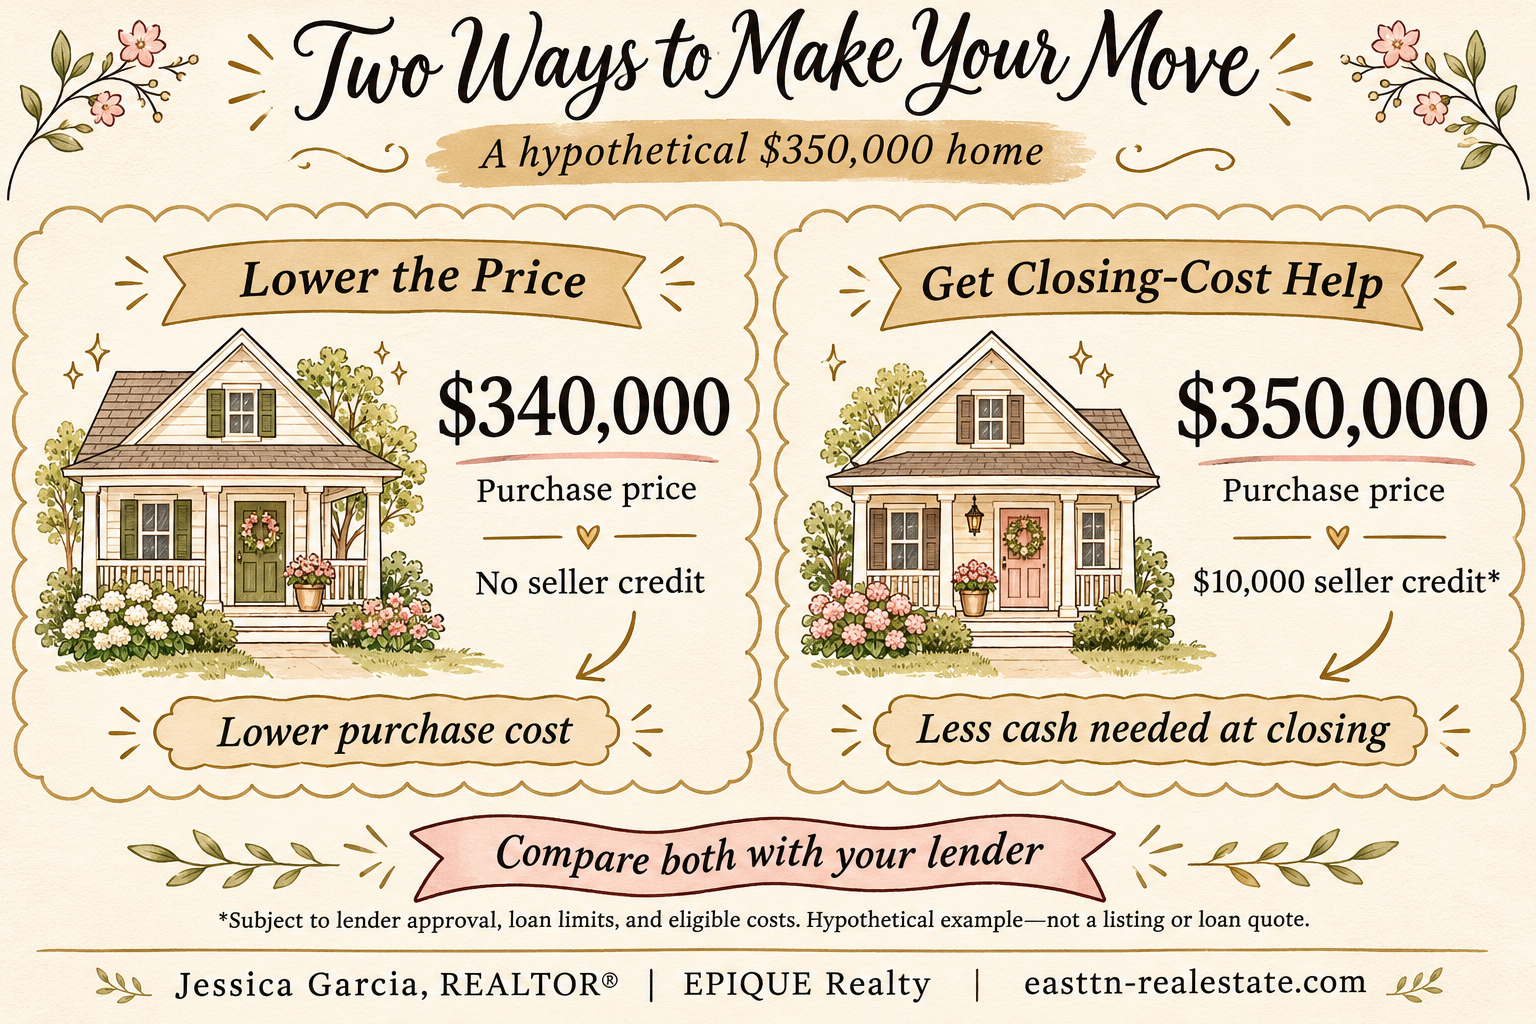
The $340,000 offer gives you a lower purchase price. The $350,000 offer with a $10,000 seller credit could reduce your upfront cash requirement while leaving you with a higher purchase price and potentially a larger loan.
Neither automatically wins.
Before deciding, ask your lender to compare:
- Your estimated monthly payment.
- Your total cash needed at closing.
- Your loan amount and down payment.
- Any differences in mortgage insurance, fees, or other loan terms.
We should also compare the seller’s estimated proceeds. Offers that look similar at first can affect the seller differently once expenses are included.
Can closing-cost help lower your interest rate?
Depending on your loan and the negotiated terms, an eligible seller contribution may help pay for discount points or an approved temporary rate buydown.
The details matter.
With a temporary buydown, the payment relief lasts for a defined period. Make sure the full payment afterward fits your budget.
With discount points, you pay an upfront cost for a lower interest rate. Ask your lender to explain the cost, the monthly savings, and how long it would take for those savings to recover the expense.
Look beyond the lowest first payment. Understand what you’ll owe later and what you’re paying upfront to get that benefit.
You can sometimes negotiate both
Your offer might include a price reduction and some closing-cost assistance.
Whether that works depends on the property, competing offers, the seller’s priorities, and what your financing allows.
This is where we look beyond the asking price. We review comparable sales, the home’s condition, its listing history, and the terms that could make an offer workable for everyone.
A price reduction alone doesn’t establish a home’s value or guarantee the seller will accept another concession.
My advice: get the comparison before you make the offer
When you’re buying in Maryville or elsewhere in Blount County, your offer should support your budget after closing, too.
Keeping savings available may matter more to one buyer. Reducing the loan amount may matter more to another.
Let’s have your lender run both options before we decide what to ask for. You deserve to understand what the offer means for your cash today and your payment going forward.
Want help comparing your options?
Message me “COMPARE.” I’ll help you and your lender compare a lower purchase price with closing-cost assistance on a home you’re considering.
— Jessica Garcia, REALTOR®
EPIQUE Realty
865-970-9009 • 888-893-3537
easttn-realestate.com
Helping You Close with Confidence—and a Smile!
Examples are hypothetical. Seller contributions, eligible expenses, and buydown options depend on your loan program and lender approval.
Categories
Recent Posts


GET MORE INFORMATION